Shariah Advisory & Screening Methodology
Supervised by Mufti Abu Muhammad Ali Asghar Attari Madani and Halal Economy Advisory Centre (SECP Registration No. SECP/IFD/SA/220).
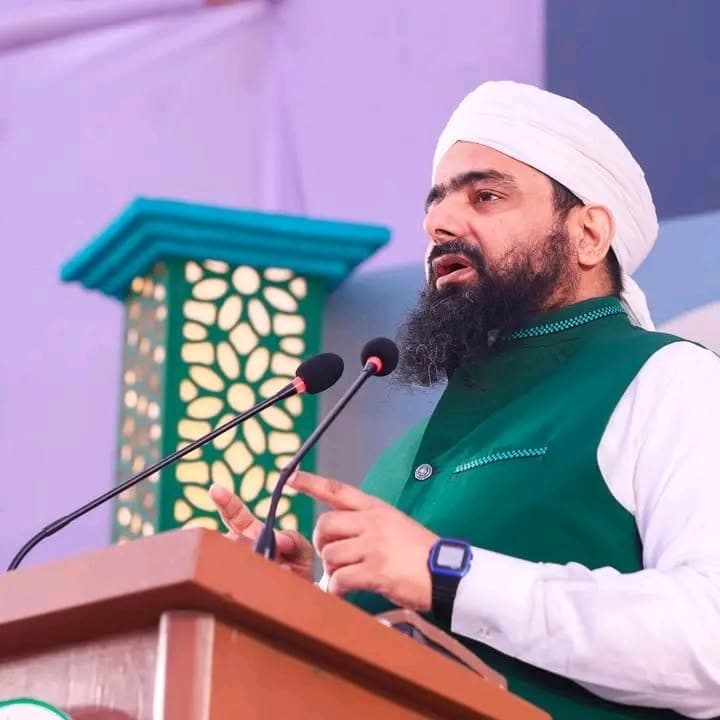
Mufti Ali Asghar
Head Shariah Advisor & Jurist
Halal Economy Advisory Centre
Authentic Guidance Grounded in
Fiqh al-Muamalat
At MRA Wiqaya, Shariah compliance is an institutional commitment embedded within every operational process. Our trading platform operates under the direct supervision of renowned Islamic jurist Mufti Abu Muhammad Ali Asghar Attari Madani and the Halal Economy Advisory Centre (HEAC).
The supervisory framework ensures that all equities made available for trading, margin controls, banking allocations, and investor trade settlements strictly comply with the Securities and Exchange Commission of Pakistan (SECP) Shariah Governance Regulations and AAOIFI standards.
Halal Economy Advisory Centre (HEAC)
HEAC is an SECP-registered Shariah advisory institution specializing in Islamic capital market structures, equity screening models, and Sukuk auditing. Its supervisory mandate ensures total operational segregation of MRA Wiqaya from conventional brokerage activities.
KMI-30 Shariah vs. KSE-100 Benchmark
Comparing 10-year historical growth dynamics, sector performance, and compounding profiles between the Shariah-compliant KMI-30 index and the conventional KSE-100 benchmark.
The 6-Tier Equity Screening Framework
Every listed company on the Pakistan Stock Exchange must fulfill all 6 benchmarks to be permissible for trading under SECP & PSX KMI-30 regulations.
| Tier | Screening Criterion | Permissible Limit | Accounting Formula & Fiqhi Foundation |
|---|---|---|---|
| 01 | Core Business Activity Core operations must be permissible under Shariah law | 100% Halal | Prohibition of investing in entities whose primary enterprise is unlawful (Haram), such as conventional banking, interest-based insurance, alcohol, tobacco, gambling, or non-halal entertainment. |
| 02 | Debt to Total Assets Total Interest-Bearing Debt / Total Assets < 37% | < 37% | Minimizing association with Riba. When conventional borrowings exceed 37% of the company's total assets, equity participation is deemed impermissible under PSX KMI-30 benchmarks. |
| 03 | Non-Compliant Investments Interest-Bearing Investments / Total Assets < 33% | < 33% | Ensures enterprise capital is actively deployed in real commercial operations rather than earning passive returns from conventional interest deposits or debt securities. |
| 04 | Non-Compliant Gross Revenue Non-Permissible Income / Total Gross Revenue < 5% | < 5% | Under the legal maxim of Al-Mashaqqah Tajlib al-Taysir (Hardship brings ease), incidental non-operating income under 5% is tolerated, provided it is 100% purified by the investor. |
| 05 | Illiquid to Total Assets Illiquid (Physical) Assets / Total Assets >= 25% | >= 25% | Bai al-Sarf: If a company consists primarily of monetary receivables and cash, shares can only be traded at par value. For shares to trade at market price, tangible assets must dominate. |
| 06 | Net Liquid Assets vs Market Price Market Price per Share > (Liquid Assets - Total Liabilities) / Shares | Price > Net Liquid Assets | Prevents monetary arbitrage. The market price paid per share must exceed the net monetary surplus, ensuring the investor is paying for enterprise goodwill and productive operations. |
Core Business Activity
Prohibition of investing in entities whose primary enterprise is unlawful (Haram), such as conventional banking, interest-based insurance, alcohol, tobacco, gambling, or non-halal entertainment.
Debt to Total Assets
Minimizing association with Riba. When conventional borrowings exceed 37% of the company's total assets, equity participation is deemed impermissible under PSX KMI-30 benchmarks.
Non-Compliant Investments
Ensures enterprise capital is actively deployed in real commercial operations rather than earning passive returns from conventional interest deposits or debt securities.
Non-Compliant Gross Revenue
Under the legal maxim of Al-Mashaqqah Tajlib al-Taysir (Hardship brings ease), incidental non-operating income under 5% is tolerated, provided it is 100% purified by the investor.
Illiquid to Total Assets
Bai al-Sarf: If a company consists primarily of monetary receivables and cash, shares can only be traded at par value. For shares to trade at market price, tangible assets must dominate.
Net Liquid Assets vs Market Price
Prevents monetary arbitrage. The market price paid per share must exceed the net monetary surplus, ensuring the investor is paying for enterprise goodwill and productive operations.
Dividend Purification Protocol
When a screened company earns incidental non-operating income (e.g., interest on operational current accounts or bank guarantees), Shariah requires investors to purge that exact proportion of their dividend income into charity.
Purification Calculation Formula
Example: If an investor receives Rs. 50,000 in dividends from an equity where non-compliant income represents 1.5% of gross revenue, the purified charity amount is Rs. 750 (Rs. 50,000 × 1.5%). The remaining Rs. 49,250 is 100% pure halal income.
MRA Wiqaya publishes quarterly audited Shariah Screening reports for all PSX KMI-30 constituents detailing the exact non-compliant income ratio to apply to declared dividends.
Disbursement Rules Under Islamic Law
- The purified amount must be disbursed to recognized charities or public welfare projects.
- The disbursement must be made without the intention of religious reward (Thawab), strictly to cleanse the wealth of non-halal traces.
- Purification is calculated exclusively on dividends received. Capital gains on the sale of shares in screened companies do not require purification.
The Shariah Governance & Audit Process
How MRA Wiqaya ensures ongoing compliance from the moment an order is entered to quarterly regulatory reporting.
Pre-Trade OMS Filtering
Every order submitted through the trading terminal is automatically validated against the active list of SECP/PSX Shariah-compliant equities. Orders for non-compliant companies are blocked in real-time.
Physical Settlement & Zero Margin Debt
Transactions are executed strictly on a cash-delivery basis (T+2). Conventional leverage (MTS/Badla), margin financing, and blank short sales are permanently disabled at the platform architecture level.
Segregated Islamic Banking Reserves
All client funds are placed strictly in non-interest-bearing, segregated Islamic bank accounts with Meezan Bank, BankIslami, and Faysal Islamic Bank, with no co-mingling with conventional funds.
Quarterly Supervisory Shariah Audits
Independent Shariah scholars from the Halal Economy Advisory Centre conduct quarterly compliance audits of trading logs, bank statements, and account ledgers to issue formal compliance certificates.